By Isabella ·
How to Teach Kids Money Skills Before the Teen Years
Help children build money skills through everyday choices, short check-ins, saving goals, budgeting practice, and digital-payment safety.
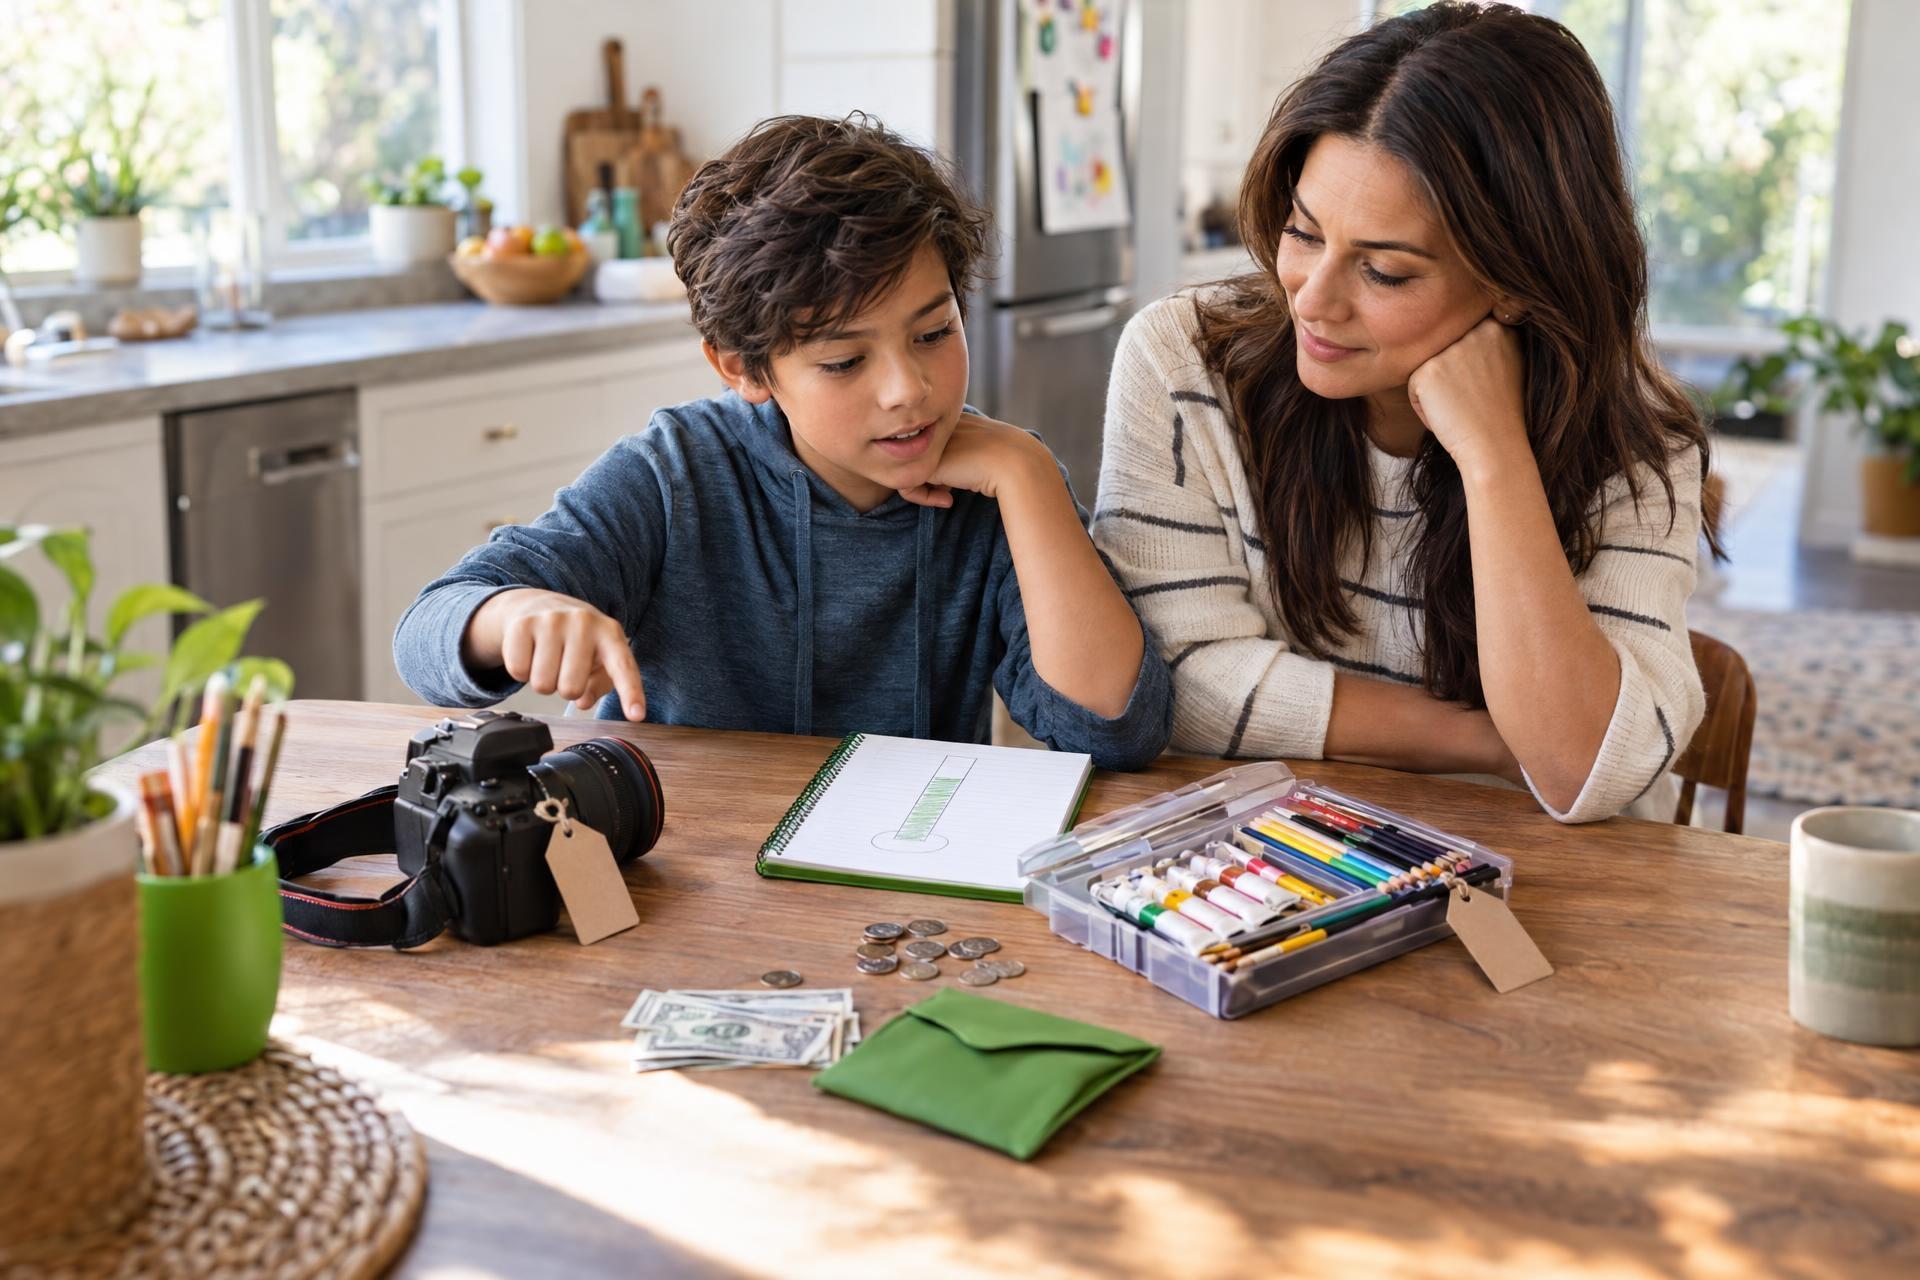
“Can I buy this?” can feel like a question with only two possible answers: yes or no. But it can also be a small, useful opening for teaching money skills.
Children do not need a formal finance course, a bank account, or a large allowance to start learning how money works. They need repeated chances to make manageable choices: saving for an art kit, comparing two snacks at the store, deciding whether a game add-on is worth it, or planning what to do with birthday money.
The goal is not to make children worry about adult finances or become perfect savers. It is to help them practice a habit they will use for years: pause, gather information, make a choice, and learn from what happens next.
Money skills grow through small, real decisions rather than one big lesson. Help your child name a goal, find the full cost, compare options, notice the trade-off, make a plan, and reflect on the result. A short weekly check-in, an appropriately sized budget, and room for low-stakes mistakes can make spending, saving, and digital safety feel practical instead of stressful. The aim is not to manage adult finances; it is to build judgment, one choice at a time.
Start with decisions kids can actually see
Money can seem abstract when children only hear adults say that something is “too expensive” or “not in the budget.” It becomes more understandable when connected to a decision that matters to them.
Look for ordinary moments where a child has a real stake in the outcome:
- A desired toy, book, game, or art supply
- Birthday or holiday money
- A small snack or grocery budget
- Supplies for a hobby, sport, or creative project
- Money earned from an age-appropriate task, pet sitting, or babysitting
- An online purchase with shipping, add-ons, or subscription costs
These moments are more effective than a lecture because the child has a reason to pay attention. Rather than immediately deciding for them, try shifting the conversation from “Should I let you buy this?” to “How will you decide whether this is the best use of your money?”
A simple decision process children can use again and again
Children do not need complicated spreadsheets to make a thoughtful choice. A short sequence can give them language for thinking things through.
- Name the goal. What do you want to buy, save for, or do?
- Find out the real cost. How much does it cost altogether? For online purchases, check shipping, tax, add-ons, or recurring charges when relevant.
- Consider the choices. Is there another brand, size, store, or way to reach the goal?
- Notice the trade-off. If you use the money here, what will you not be able to do with it?
- Make a plan. Will you buy it now, wait, save a certain amount each week, or choose something else?
- Reflect afterward. Did the choice work out the way you expected? What would you do differently next time?
Imagine an 8-year-old who wants a $20 art kit. Help them count what they already have, decide how much to put aside each week, and mark their progress on a paper tracker. The lesson is not simply “save money.” It is that a goal can become a plan made of small steps.
For an 11-year-old comparing a game or hobby item online, the same process may mean checking two stores and looking at the total cost rather than only the sticker price.
For a 13-year-old facing an impulse purchase, it may mean taking a 24-hour pause before deciding whether the item still matters more than a larger goal.
Use a five-minute family money routine
One big “money talk” can feel awkward for both parent and child. A brief, predictable check-in is usually easier to sustain and gives children time to practice between conversations.
Choose a low-pressure moment once a week: during a car ride, while setting the table, after a grocery trip, or on a weekend morning. Keep the tone curious rather than corrective. You can ask:
Four questions for a weekly check-in
- What money came in this week, if any?
- What are you saving or planning for right now?
- Is there a purchase or choice coming up?
- What did you notice about a choice you made last week?
- Do you need help finding out the full cost or comparing options?
Not every child will have money coming in each week, and that is fine. The conversation can use pretend scenarios, a household shopping decision, or an upcoming gift occasion. The important part is practicing the thinking, not having a particular financial product or system.
Try to make the routine a no-shame zone. “What did you learn?” is more useful than “Why did you waste your money?”
What money skills can look like at different ages
There is no single checklist every child must finish by a certain birthday. Children develop at different rates, and family circumstances vary. Still, it helps to offer the next useful level of responsibility rather than expecting an 8-year-old and a 15-year-old to handle the same concepts.
| Age range | Useful focus | Everyday practice idea |
|---|---|---|
| 8–10 | Needs versus wants, limited resources, short-term saving, and price comparison | Give your child a small budget for one grocery category and ask them to explain their choice among brands, sizes, and prices. |
| 11–13 | Simple budgeting, money in and money out, trade-offs, and total purchase cost | Track one month of allowance, gift money, or earnings in a notebook or notes app: money received, spending, and savings. |
| 14–15 | Earnings, saving plans, basic banking concepts, payment methods, and digital safety | If your child earns money from babysitting or pet sitting, discuss what portion they want to save and what details should stay private when payment is digital. |
At any age, the adult’s job is to keep the decision appropriately sized. A child can choose between two snack options or plan for a hobby purchase without being asked to manage household bills. As children grow, their choices can gradually become more independent and more complex.
Let low-stakes mistakes do some teaching
It is understandable to want to protect a child from buyer’s remorse. But if the stakes are small and the boundaries are sensible, an occasional disappointing purchase can be useful information.
Maybe your child spends all their birthday money on a trendy item and loses interest a week later. You do not need to say, “I told you so,” or rush to replace the money. A calm conversation can turn the experience into practice:
- Would you make the same choice again?
- What did you like about it, and what disappointed you?
- What would you want to know before buying something similar next time?
- Would a waiting period, price comparison, or savings goal help next time?
This approach does not mean leaving children on their own with every decision. Parents still set limits around safety, family values, and what is appropriate. It simply makes room for children to develop judgment instead of relying only on an adult’s approval.
Make digital money safety part of the conversation
For older children especially, money may feel less like cash and more like a tap, a saved card, a payment request, or an in-game purchase. That makes it important to discuss protection alongside spending and saving.
Keep the guidance straightforward and practical:
- Do not share passwords, account numbers, card details, or verification codes.
- Pause before responding to an urgent-looking message, payment request, or offer that seems confusing.
- Ask a trusted adult before entering payment information, clicking an unfamiliar link, or accepting digital payment from someone they do not know well.
- Check what a purchase includes and whether it may repeat automatically.
- Know what to do if a card, device, or account access is lost: tell a parent or trusted adult promptly.
The aim is not to make digital payments sound frightening. It is to build the habit of slowing down and asking for help when something does not feel clear.
Keep it family-specific, not comparative
Money conversations can easily become loaded when children compare what friends have, what other families buy, or how much someone else earns. A helpful response brings the focus back to the decision in front of your child.
You might say, “Different families make different choices with money. Let’s look at what matters for your goal and our plan.” This keeps the conversation values-neutral while still teaching that resources are limited and choices involve trade-offs.
If your family likes a simple system, a child receiving gift money could choose how much to use now and how much to save for later. Some families also include giving; others do not. There is no required formula. A plan works best when your child understands it and has a meaningful amount of choice within it.
What parents can do next
Major financial-literacy frameworks commonly include earning, spending, saving and investing, borrowing, and protecting money. That may sound like a lot, but parents do not need to teach every topic at once—or turn childhood into a finance seminar.
- Choose one upcoming, real decision: a grocery choice, birthday money, a hobby purchase, or an online item.
- Use the simple process: name the goal, find the full cost, compare options, notice the trade-off, make a plan, and reflect afterward.
- Set aside five minutes each week for a curious, no-shame check-in.
- Keep choices appropriately sized, and let manageable disappointments become information for the next decision.
- Include one practical reminder about protecting personal and payment information online.
Start with the next real decision. Over time, those small conversations can build familiarity, confidence, and better decision-making habits for the greater independence ahead.
Practice money skills through guided challenges
If your child enjoys learning through discussion and hands-on challenges, Undoschool offers guided, age-appropriate practice.
Helpful parent resources
For more age-appropriate conversation starters and activities, the Consumer Financial Protection Bureau’s Money as You Grow resource and the FDIC’s Money Smart for Young People materials offer useful starting points. The National Standards for Personal Financial Education also outlines the broad skills children can build over time.